Detailed Comparison between NPS vs ELSS Funds
Published: 14 Oct 2026
NPS and ELSS are both market-linked investment options, but they serve different financial needs. NPS mainly focuses on retirement planning, while ELSS is an equity mutual fund that offers tax-saving benefits under applicable rules. The NPS vs ELSS comparison becomes important when investors look at returns, risk, lock-in, liquidity, tax benefits, and withdrawal rules. Understanding these differences can help you choose an option that matches your long-term goals.
1. What Is NPS?
The National Pension System, or NPS, is a market-linked retirement investment option designed to help people build savings for their old age. Subscribers can contribute regularly and invest their money across equity, corporate bonds, government securities, and other permitted assets. In the NPS vs ELSS comparison, NPS mainly focuses on retirement planning, while ELSS focuses more on equity growth and tax saving.
1. Retirement-Focused Investment
NPS is mainly created to help subscribers build a long-term retirement corpus. Its withdrawal rules encourage people to keep their money invested for many years. This makes it suitable for investors who want disciplined retirement planning.
2. Market-Linked Returns
NPS does not offer fixed or guaranteed returns. Its performance depends on market conditions, asset allocation, and the selected Pension Fund Manager. A higher equity share may improve growth potential, but it also increases market risk.
3. Different Asset Classes
NPS invests money across different asset classes. These mainly include equity, corporate bonds, government securities, and other approved investments. This mix can provide a balance between growth and stability.
4. Active Choice and Auto Choice
Under Active Choice, subscribers select their preferred asset allocation within the permitted limits. Under Auto Choice, the allocation changes automatically according to the subscriber’s age. Auto Choice may suit beginners who do not want to manage their portfolio manually.
5. Tier 1 and Tier 2 Accounts
Tier 1 is the main retirement account and follows stricter withdrawal rules. Tier 2 is a voluntary account that generally provides easier access to money. For the NPS vs ELSS comparison, Tier 1 is more relevant because it offers retirement-related tax benefits under applicable rules.
2. What Is ELSS?
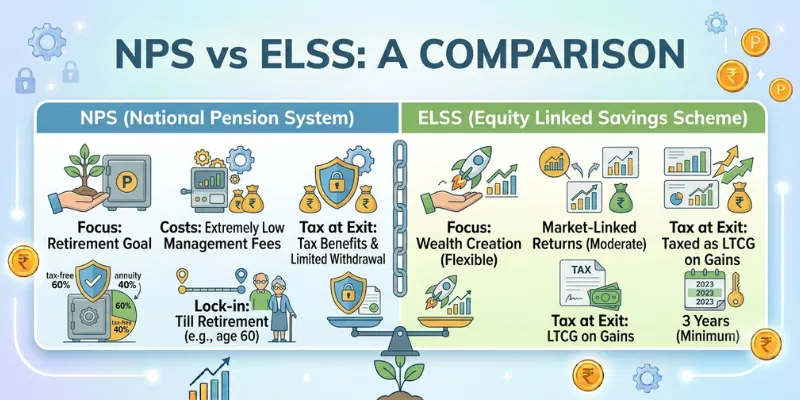
ELSS stands for equity linked savings scheme. It is a tax-saving mutual fund that invests mainly in company shares and equity-related assets. In the NPS vs ELSS comparison, ELSS offers higher equity exposure and easier access after the lock-in period, while NPS follows a more retirement-focused structure.
1. Equity-Based Investment
ELSS invests most of its money in equity and equity-related securities. This gives it strong long-term growth potential. However, its value can rise or fall sharply with the stock market.
2. Three-Year Lock-In Period
Every ELSS investment has a compulsory lock-in of three years. If you invest through SIP, each monthly instalment gets its own separate three-year lock-in. You cannot redeem those units before their lock-in ends.
3. Tax-Saving Benefit
Eligible elss investments may qualify for deduction under Section 80C when the investor uses the old tax regime. This deduction is part of the overall Section 80C limit. ELSS does not provide the separate additional deduction available with certain NPS contributions.
4. SIP and Lump-Sum Options
Investors can put money into ELSS through a 97q
5. Professional Fund Management
An Asset Management Company manages the ELSS portfolio through a professional fund manager. The manager selects shares according to the scheme’s investment objective. Investors should compare the fund’s risk, long-term performance, expense ratio, and portfolio before investing.
3. NPS vs ELSS Comparison
NPS and ELSS are both long-term, market-linked investment options, but they serve different purposes. NPS mainly focuses on retirement planning, while ELSS combines equity investment with tax-saving benefits. The following NPS vs ELSS comparison explains their major differences.
| Comparison Point | NPS | ELSS |
|---|---|---|
| Main purpose | Retirement planning | Tax saving and wealth creation |
| Investment type | Mix of equity and debt | Mainly equity |
| Lock-in | Retirement-focused restrictions | Three years for each investment |
| Risk level | Depends on asset allocation | Generally high |
| Withdrawal | Limited and rule-based | Allowed after the lock-in ends |
| Annuity | May apply at exit | No compulsory annuity |
1. Purpose and Investment Structure
NPS is designed mainly to help subscribers create a retirement corpus. It invests across equity, corporate bonds, government securities, and other permitted assets. ELSS mainly invests in equity and may suit investors seeking long-term growth with tax-saving eligibility.
2. Lock-In and Liquidity
nps tier 1 follows long-term withdrawal and exit rules because it is a retirement account. ELSS has a three-year lock-in for every investment, including each SIP instalment. After the lock-in ends, ELSS investors can redeem eligible units more easily.
3. Risk and Return Potential
NPS risk depends on the selected equity and debt allocation. ELSS usually carries greater market risk because most of its portfolio remains invested in company shares. This higher equity exposure may offer stronger growth potential, but returns are not guaranteed.
4. Retirement Income and Flexibility
NPS may require part of the corpus to follow applicable annuity or retirement-income rules at exit. ELSS does not require an annuity, so investors can decide how to use their money after redemption. In the NPS vs ELSS comparison, NPS offers stronger retirement discipline, while ELSS provides greater flexibility.
4. Difference in Investment Options
The investment choices available in NPS and ELSS are quite different. NPS allows subscribers to spread money across equity and debt assets, while ELSS mainly focuses on equity investment. This difference affects risk, return potential, and portfolio control.
1. Investment Options in NPS
NPS allows investment in equity, corporate bonds, government securities, and other permitted assets. Subscribers can select their own allocation under Active Choice or use Auto Choice for age-based management. This gives NPS a more balanced investment structure.
2. Investment Options in ELSS
ELSS mainly invests in equity and equity-related securities. The fund manager selects shares according to the scheme’s investment objective. Investors cannot directly decide how much money should go into debt or equity within the same ELSS scheme.
3. Choice of Fund Manager
NPS subscribers can choose from available Pension Fund Managers and may change the manager under applicable rules. ELSS investors choose a mutual fund scheme managed by an Asset Management Company. Changing the ELSS fund usually means investing future money in another scheme because locked units cannot be freely moved.
4. Control Over Asset Allocation
NPS gives subscribers some control over the mix of equity and debt through Active Choice. Auto Choice can also manage the allocation automatically based on age. ELSS provides less control over asset allocation because the fund remains mainly equity-based.
5. Range of Investment Styles
NPS offers limited but structured options designed mainly for retirement. ELSS schemes may follow different equity styles, such as large-cap, multi-cap, value, or growth-focused strategies. This gives ELSS investors more variety within equity investing.
Overall, the main difference in NPS vs ELSS investment options is that NPS provides a mix of asset classes, while ELSS mainly offers equity exposure. NPS may suit investors who want diversification, while ELSS may suit those seeking higher equity participation.
5. NPS vs ELSS Returns
Returns from NPS and ELSS are market-linked, so neither option provides fixed or guaranteed growth. In the NPS vs ELSS comparison, returns mainly depend on equity exposure, market performance, investment period, fund management, and total costs. ELSS may offer higher growth potential, while NPS may provide a more balanced return through equity and debt investments.
1. How NPS Generates Returns
NPS invests money across equity, corporate bonds, government securities, and other permitted assets. Its returns depend on the selected asset allocation and Pension Fund Manager. A higher equity share may improve long-term growth potential but also increases market risk.
2. How ELSS Generates Returns
ELSS invests mainly in company shares and equity-related securities. Its performance depends on stock market movements, portfolio quality, fund strategy, and expenses. Since ELSS keeps high equity exposure, its value may rise or fall sharply in the short term.
3. Which Can Offer Higher Returns?
ELSS may offer higher return potential because most of its portfolio remains invested in equity. NPS usually contains a mix of growth and stable assets, so its return may be more moderate. However, higher potential returns in ELSS also come with greater volatility and loss risk.
4. Effect of Asset Allocation
Asset allocation plays an important role in NPS returns. An equity-heavy NPS portfolio may perform differently from a conservative NPS option with more government securities. ELSS has less asset-allocation flexibility because it remains mainly equity-based.
5. Effect of Investment Period
Both options may benefit from a long investment period. Staying invested for many years gives the portfolio more time to recover from temporary market falls. Investors should not judge either option only from one-year or short-term performance.
6. Effect of Charges
NPS generally follows a low-cost fund management structure. ELSS charges an expense ratio, which may be higher in regular plans than direct plans. Lower costs can help investors retain a larger part of their long-term returns.
7. Return Stability
NPS may provide better stability when a meaningful part of the portfolio is invested in bonds and government securities. ELSS can experience larger ups and downs because of its high equity exposure. Therefore, ELSS may suit investors who can handle greater market fluctuations.
8. Guaranteed Returns
Neither NPS nor ELSS guarantees a fixed return. Their performance can change because of market conditions, interest rates, economic events, and portfolio decisions. Investors should not treat either option like a fixed deposit.
Overall, the NPS vs ELSS Returns comparison shows that ELSS may provide higher growth potential, while NPS may offer a better balance between growth and stability. The right option depends on your risk capacity, investment period, retirement goal, and need for flexibility.
6. NPS vs ELSS Risk Comparison
Both NPS and ELSS carry market risk, but their risk levels are different. NPS can divide money between equity and debt assets, while ELSS mainly invests in company shares. The following NPS vs ELSS risk comparison explains the major differences.
| Risk Point | NPS | ELSS |
|---|---|---|
| Overall risk | Low to high, based on allocation | Generally high |
| Equity exposure | Limited and adjustable | Mainly equity-based |
| Market fluctuations | Usually lower with debt allocation | Usually higher |
| Risk reduction | Possible through Auto Choice | No automatic age-based reduction |
| Short-term loss risk | Depends on selected asset mix | Can be significant |
| Suitable investor | Low, moderate, or high-risk investor | Investor with high risk tolerance |
1. Equity Market Risk
NPS risk depends on how much money is invested in equity. A subscriber can reduce market risk by keeping more money in corporate bonds and government securities. ELSS remains mainly equity-based, so its value may rise or fall sharply with the stock market.
2. Asset Diversification Risk
NPS provides diversification across equity, corporate bonds, and government securities. This mix can reduce dependence on one asset class. ELSS also invests across different companies, but most of its portfolio remains linked to equity-market performance.
3. Age-Based Risk Reduction
NPS offers Auto Choice, which can gradually reduce equity exposure as the subscriber gets older. This may lower market risk closer to retirement. ELSS does not automatically reduce risk according to age, so the investor must manage the portfolio separately.
4. Which Option Is Riskier?
ELSS is generally riskier because of its high equity exposure. NPS may be less volatile when the subscriber selects a balanced or debt-heavy allocation. However, an equity-heavy NPS portfolio can also face noticeable market losses.
Overall, the NPS vs ELSS risk comparison shows that NPS offers more control over risk through asset allocation. ELSS may suit investors who can handle stronger market fluctuations and remain invested for the long term.
7. NPS vs ELSS Costs and Charges
NPS and ELSS both include investment-related costs, but their charge structures are different. NPS may include several small account and service fees, while ELSS mainly charges an expense ratio through the mutual fund.
1. NPS Costs and Charges
- Fund management fee: NPS charges a small fee for managing the subscriber’s equity and debt investments.
- CRA charges: The Central Recordkeeping Agency may charge for account maintenance, records, and transactions.
- PoP charges: Subscribers linked to a Point of Presence may pay onboarding and account-service fees.
- Payment charges: Online contributions may include net banking, debit-card, credit-card, or other gateway costs.
- Trust and custodian expenses: Small charges may be adjusted through the scheme’s assets for supervision and asset custody.
2. ELSS Costs and Charges
- Expense ratio: The fund deducts an annual expense for managing and operating the ELSS scheme.
- direct plan cost: Direct plans generally have lower expenses because they do not include distributor commission.
- regular plan cost: Regular plans usually cost more because the expense ratio includes distribution-related charges.
- Transaction costs: Small platform, brokerage, or payment-related charges may apply depending on the investment channel.
- Tax on gains: Eligible capital gains may be taxable when ELSS units are redeemed after the lock-in period.
Overall, NPS generally has a low fund management cost but may include several account-level fees. ELSS has a simpler cost structure, but its expense ratio can reduce long-term returns, especially in regular plans.
8. Advantages and Disadvantages of NPS
NPS offers disciplined retirement planning, tax benefits, and a mix of equity and debt investments. However, it also has strict withdrawal rules and less flexibility than ELSS.
1. Advantages of NPS
- Retirement-focused investment: NPS helps subscribers build a dedicated corpus for life after retirement.
- Low-cost management: Its fund management charges are generally low compared with many market-linked options.
- Tax benefits: Eligible personal and employer contributions may provide deductions under applicable tax rules.
- Asset diversification: Subscribers can invest across equity, corporate bonds, and government securities.
- Automatic allocation option: Auto Choice can adjust the investment mix according to the subscriber’s age.
2. Disadvantages of NPS
- Limited liquidity: Tier 1 money cannot be withdrawn freely whenever the subscriber needs it.
- Complex exit rules: Normal exit, premature exit, and partial withdrawal follow separate conditions.
- Annuity requirement: Part of the corpus may need to be used for an annuity or another approved retirement-income option.
- Lower investment flexibility: NPS offers fewer fund choices and asset classes than many mutual fund options.
- Market-linked returns: Returns are not guaranteed and can change with equity and bond market performance.
9. Advantages and Disadvantages of ELSS
ELSS offers tax-saving benefits, high equity exposure, and better liquidity after the lock-in period. However, it also carries market risk and may not suit investors who want stable or guaranteed returns.
1. Advantages of ELSS
- Tax-saving benefit: Eligible ELSS investments may qualify for deduction under Section 80C under applicable tax rules.
- Higher growth potential: ELSS invests mainly in equity, which can support long-term wealth creation.
- Shorter lock-in: ELSS has a three-year lock-in, which is shorter than the retirement-focused restrictions in NPS.
- SIP and lump-sum options: Investors can invest regularly through SIP or add a larger amount at one time.
- Greater withdrawal flexibility: After the lock-in ends, eligible units can be redeemed without any compulsory annuity.
2. Disadvantages of ELSS
- High market risk: ELSS invests mainly in shares, so its value can rise or fall sharply.
- No guaranteed returns: The final return depends on stock market performance and fund management.
- Separate SIP lock-in: Every SIP instalment has its own three-year lock-in period.
- No additional NPS-style deduction: ELSS does not offer the separate additional deduction available for certain NPS contributions.
- No built-in retirement income: Investors must plan their own withdrawals because ELSS does not automatically provide a pension.
10. Tips for Choosing Between NPS and ELSS
Choosing between NPS and ELSS should depend on your financial goal, risk level, and need for access to money. These simple tips can help you make a better decision.
- Check your main goal: Choose NPS for dedicated retirement planning and ELSS for tax saving with long-term equity growth.
- Understand your risk level: ELSS may suit investors who can handle higher market fluctuations, while NPS allows a more balanced equity and debt mix.
- Compare the lock-in rules: NPS follows retirement-focused withdrawal rules, while ELSS has a three-year lock-in for every investment.
- Review your tax regime: Check whether NPS or ELSS deductions are useful under your selected tax regime before investing for tax benefits.
- Consider using both: You may use NPS for retirement discipline and ELSS for additional equity exposure and better flexibility after the lock-in period.
NPS may be better for people who want a dedicated and disciplined retirement plan. ELSS may suit investors who want higher equity exposure and greater flexibility after the lock-in period. The better option depends on your retirement goal, risk level, and liquidity needs.
ELSS may offer higher return potential because it invests mainly in equity. NPS usually invests across equity and debt, so its returns may be more balanced. However, neither option guarantees returns.
ELSS has a three-year lock-in for every investment. NPS Tier 1 follows retirement-focused withdrawal and exit rules. Therefore, ELSS generally provides easier access to money after its lock-in ends.
Yes, you can invest in both options at the same time. NPS can support disciplined retirement saving, while ELSS can provide additional equity exposure. Using both may help balance retirement planning and investment flexibility.
NPS may provide additional tax benefits on eligible personal and employer contributions. ELSS may qualify for deduction under Section 80C under applicable old tax regime rules. The better choice depends on your tax regime, income, and employment benefits.
Conclusion
So guys, in this article, we’ve covered NPS vs ELSS in detail. We discussed their investment structure, returns, risk, tax benefits, lock-in rules, costs, advantages, and disadvantages. In my opinion, NPS may suit investors who want disciplined retirement planning, while ELSS may suit those seeking higher equity exposure and better flexibility after three years. You can also use both options for different parts of your long-term financial plan. Review your goals, tax regime, and risk capacity today before choosing the right investment.
The information and calculators on Finance Calculatorz are provided for educational purposes only. Calculator results are estimates and may not always be fully accurate. This content is not financial, investment, tax, or legal advice. Please consult a qualified professional before making any financial decision.
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
