CAGR vs XIRR? Which is Best for Investor?
Published: 23 Oct 2026
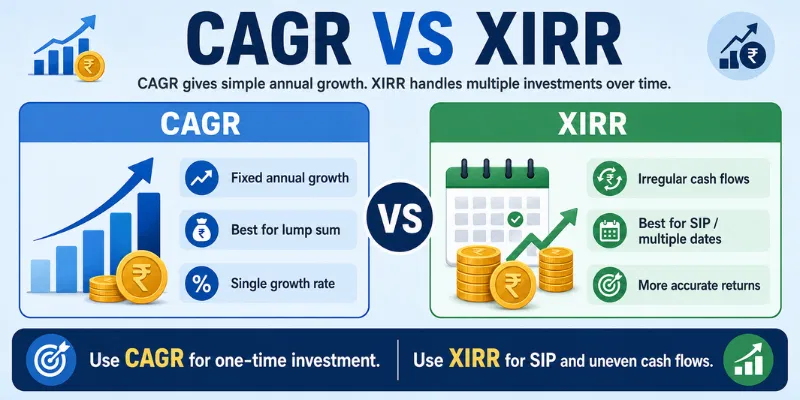
CAGR and XIRR are two common methods used to measure annualized investment returns. CAGR works best when there is one initial investment and one final value, while XIRR is more suitable for multiple investments or withdrawals made on different dates. Both methods show returns as a yearly percentage, but they use different calculation approaches. Understanding CAGR vs XIRR can help investors choose the right method for lump sum investments, SIPs, mutual funds, and portfolios.
1. What Is CAGR vs XIRR?
CAGR stands for compound annual growth rate and measures the average yearly growth of an investment over a selected period. It uses one beginning value, one ending value, and the total number of years. This method is mainly suitable for a lump sum investment with no additional deposits or withdrawals. It assumes that the investment grew at a steady compounded rate each year. However, the actual yearly returns may have been higher, lower, or negative. CAGR makes long-term investment growth easier to understand and compare.
XIRR stands for Extended Internal Rate of Return and calculates annualized returns when multiple cash flows occur on different dates. It considers every investment, withdrawal, dividend, and final portfolio value along with its exact transaction date. This method is commonly used for SIPs, mutual funds, stocks, and complex portfolios. Each investment is treated as a negative cash flow, while withdrawals and the final value are treated as positive cash flows. The main difference in CAGR vs XIRR is that CAGR suits simple lump sum growth, while XIRR suits multiple or irregular transactions. Therefore, the correct method depends on how and when money moves in or out of the investment.
2. Working of CAGR vs XIRR
CAGR works by comparing the beginning value of an investment with its ending value over a specific number of years. It calculates the steady annual growth rate needed for the starting amount to reach the final amount through compounding. The method uses only three values: the initial amount, final value, and investment duration. It does not consider extra deposits, withdrawals, or the exact dates of transactions. Actual yearly returns may rise or fall, but the result is shown as one smooth annual percentage. This makes CAGR useful for measuring the long-term growth of a simple lump sum investment.
XIRR works by including every investment, withdrawal, dividend, and final portfolio value along with its exact date. Investments are entered as negative cash flows, while withdrawals and the final value are entered as positive cash flows. It calculates how long each amount remained invested before finding one annualized return. This approach makes it suitable for SIPs and portfolios with multiple or irregular transactions. In CAGR vs XIRR, the first method focuses on growth between two values, while the second studies the timing of all cash flows. Therefore, XIRR usually gives a more realistic result when money moves in or out several times.
3. Calculation in CAGR vs XIRR
1. CAGR Calculation
CAGR calculation requires only three values: the beginning value, ending value, and total investment period. Its formula is:
CAGR = [(Ending Value ÷ Beginning Value)^(1 ÷ Number of Years) − 1] × 100
For example, suppose ₹1,00,000 grows to ₹1,50,000 in three years:
CAGR = [(₹1,50,000 ÷ ₹1,00,000)^(1 ÷ 3) − 1] × 100
The result is approximately 14.47% per year. This means the investment grew at an average compounded annual rate of 14.47%, although its actual return may have changed each year. A CAGR Calculator can provide the result quickly and reduce manual errors.
2. XIRR Calculation
XIRR calculation requires every investment, withdrawal, final portfolio value, and exact transaction date. Investments are entered as negative values, while withdrawals and the final value are entered as positive values.
In Excel or Google Sheets, use:
=XIRR(A2:A5, B2:B5)
The function calculates one annualized return after considering how long each payment remained invested. In CAGR vs XIRR, CAGR is easier to calculate because it uses only three values, while XIRR requires complete cash-flow details and exact dates.
4. Major Differences Between CAGR and XIRR
CAGR and XIRR are both used to measure annualized investment returns, but they work in different ways. CAGR is mainly suitable for a simple investment that has one beginning value and one ending value. XIRR is more useful when several investments, withdrawals, or other transactions happen on different dates. Understanding these differences can help investors select the correct method and avoid misleading return calculations.
1. Type of Cash Flow
CAGR is designed for a simple cash-flow pattern. It works best when an investor makes one lump sum investment and receives one final value after a specific period. It does not properly account for additional investments, withdrawals, or dividends made during that time.
XIRR can manage multiple cash flows. It includes regular sip instalments, additional investments, partial withdrawals, dividends, and the final portfolio value. This makes it more suitable for real-life portfolios where money may move in and out several times.
2. Use of Transaction Dates
CAGR uses the total investment duration, such as three, five, or ten years. It does not require the exact date on which the investment was made or redeemed. The calculation only needs the beginning value, ending value, and total number of years.
XIRR uses the exact date of every transaction. It calculates how long each amount remained invested before finding the annualized return. This is important because money invested earlier stays active longer than money invested near the end of the period.
3. Suitable Investment Type
CAGR is generally suitable for a lump sum investment with no additional cash flows. It can be used to measure the growth of stocks, mutual funds, business revenue, sales, profits, or market size over several years.
XIRR is more suitable for SIPs, irregular deposits, stock portfolios, and mutual fund accounts with multiple transactions. It gives a clearer result when investments are made at different times. In CAGR vs XIRR, the correct choice mainly depends on the investment pattern.
4. Calculation Method
CAGR uses a simple formula based on three values: beginning value, ending value, and number of years. Investors can calculate it manually or use a CAGR Calculator for faster results. The final answer shows the average compounded annual growth rate.
XIRR uses a more complex financial equation. It requires all cash-flow amounts and their matching dates. Investors normally calculate it through Excel, Google Sheets, or a financial calculator because solving it manually is difficult.
5. Treatment of Additional Investments
CAGR cannot accurately measure returns when new money is added during the investment period. For example, if an investor starts with ₹1 lakh and adds ₹50,000 later, the final value does not come only from the original investment. Using CAGR in this case may produce a misleading result.
XIRR treats every additional investment as a separate negative cash flow. It also considers the exact date on which that amount was invested. This allows it to calculate a more realistic annualized return for portfolios with repeated deposits.
6. Treatment of Withdrawals and Dividends
CAGR does not properly handle partial withdrawals or dividends received during the investment period. It only compares the starting and ending values. Leaving out these cash flows may make the return appear higher or lower than the investor’s actual performance.
XIRR includes withdrawals, dividends, and sale proceeds as positive cash flows. It considers when each amount was received and how it affected the remaining investment. This gives investors a clearer picture of the complete return earned from the portfolio.
7. Accuracy of the Result
CAGR provides a reliable result when there is one beginning amount, one ending value, and no transactions in between. It shows the smooth annual growth rate needed for the investment to reach its final value. However, it does not show yearly market fluctuations.
XIRR is usually more accurate for portfolios with multiple or irregular cash flows. It gives importance to both the amount and timing of every transaction. However, its accuracy depends on correct dates, complete records, and the latest portfolio value.
8. Ease of Calculation
CAGR is easier for beginners because it requires only three values. The formula is simple, and the result can be calculated without maintaining a complete transaction history. You can also Calculate Your CAGR online within seconds.
XIRR requires more detailed information, including every investment, withdrawal, dividend, and transaction date. Incorrect signs, missing values, or wrong dates may create an error or produce an inaccurate result. Therefore, CAGR is simpler, while XIRR is more detailed and better suited to complex investments.
5. CAGR vs XIRR Comparison Table
| Comparison Point | CAGR | XIRR |
|---|---|---|
| Full Form | Compound Annual Growth Rate | Extended Internal Rate of Return |
| Cash Flows | Uses one beginning and one ending value | Handles multiple investments and withdrawals |
| Transaction Dates | Uses only the total investment period | Uses the exact date of every transaction |
| Best Suited For | Lump sum investments | SIPs and irregular investments |
| Calculation | Simple and easy to calculate | More detailed and usually needs Excel or a calculator |
| Main Result | Shows average annual compounded growth | Shows annualized return based on all cash flows |
6. CAGR vs XIRR in SIP Investment
In a SIP, investors put money into a mutual fund at regular intervals, such as monthly or quarterly. Each instalment is invested on a different date and remains invested for a different period. Because of these multiple cash flows, cagr may not show the actual return accurately. It only compares one beginning value with one ending value and does not consider the timing of every SIP payment.
XIRR is generally more suitable for SIP investments because it uses the amount and exact date of each instalment. Every SIP payment is entered as a negative cash flow, while the current or final portfolio value is entered as a positive cash flow. It then calculates one annualized return for the complete investment. Therefore, in CAGR vs XIRR, XIRR gives a more realistic picture of SIP performance, while CAGR is better suited to a single lump sum investment.
7. CAGR vs XIRR in Mutual Funds
In mutual funds, CAGR is useful when an investor makes one lump sum investment and does not add or withdraw money during the selected period. It compares the original investment with the final fund value and shows the average annual compounded growth. This method is simple, but it may become inaccurate when the account includes sip instalments, additional purchases, or partial redemptions.
XIRR is more suitable for mutual fund investments with multiple transactions. It considers every SIP payment, lump sum addition, dividend, withdrawal, and the current fund value along with their exact dates. Therefore, in CAGR vs XIRR, CAGR works better for a simple lump sum, while XIRR provides a more realistic annualized return for active mutual fund portfolios.
8. Common Mistakes in CAGR vs XIRR
Investors often select the wrong return method or enter incomplete data while comparing investment performance. These mistakes can produce misleading results and make an investment appear better or worse than it actually is.
- Using CAGR for SIP investments: SIPs involve several payments made on different dates. XIRR is generally more suitable because it considers each instalment separately.
- Using xirr without exact dates: Incorrect or estimated transaction dates can change the annualized return. Always use the actual date of every investment and withdrawal.
- Ignoring additional cash flows: Extra deposits, dividends, and partial withdrawals must be included when calculating XIRR. Leaving them out can produce an inaccurate result.
- Entering incorrect cash-flow signs: Investments should be entered as negative amounts, while withdrawals and the final portfolio value should be positive. Reversing these signs may create an error or incorrect return.
- Choosing the wrong investment period: An incorrect number of years can affect the CAGR result. Calculate the duration carefully from the investment date to the final valuation date.
- Forgetting the current portfolio value: XIRR requires the latest portfolio value as a positive cash flow. Without it, the return calculation remains incomplete.
- Comparing different time periods: A three-year return should not be directly compared with a ten-year return. Use similar durations for a fair comparison.
9. Tips for Choosing Between CAGR and XIRR
- Use CAGR when there is one initial investment and one final value.
- Use XIRR when several deposits or withdrawals happen on different dates.
- Check the complete transaction history before calculating returns.
- Enter exact investment and withdrawal dates in the XIRR calculation.
- Use correct cash-flow signs: investments negative and returns positive.
- Include dividends, partial redemptions, and the latest portfolio value.
- Compare investments over similar periods for a fair result.
- Do not use CAGR for SIPs with multiple instalments.
- Use XIRR for mutual fund portfolios with irregular cash flows.
XIRR is generally better for SIPs because every instalment is invested on a different date. It considers the amount and timing of each payment. CAGR cannot properly measure multiple SIP cash flows.
Yes, CAGR is suitable when you make one initial investment and receive one final value. It shows the average compounded annual growth over the selected period. No additional deposits or withdrawals should occur during that time.
Yes, XIRR can also calculate returns for a lump sum investment. However, CAGR is usually simpler when there is only one investment and one final value. XIRR becomes more useful when extra transactions are added.
The results may differ because XIRR considers every cash flow and its exact date. CAGR only compares the beginning and ending values over the total period. Additional investments or withdrawals can create a larger difference.
Accuracy depends on the investment pattern. CAGR is accurate for a simple lump sum, while XIRR is more suitable for multiple or irregular cash flows. Using the wrong method may produce a misleading result.
No, both methods only measure annualized performance. They do not directly show volatility, market risk, fees, or the possibility of future losses. Investors should review these factors separately.
No, both methods describe past investment performance. Market conditions and portfolio returns may change in the future. Investors should not treat historical annualized returns as guaranteed results.
Conclusion
So guys, in this article, we’ve covered CAGR vs XIRR in detail. Both methods measure annualized returns, but they are suitable for different investment patterns. CAGR works better for a single lump sum, while XIRR is more useful for SIPs and portfolios with multiple transactions. In my opinion, you should first check how money moved in and out of your investment before selecting a return method. Review your investment history today and use the calculation that gives you a more accurate performance result.
The information and calculators on Finance Calculatorz are provided for educational purposes only. Calculator results are estimates and may not always be fully accurate. This content is not financial, investment, tax, or legal advice. Please consult a qualified professional before making any financial decision.
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
