What is Balanced Life Cycle Funds in NPS?
Published: 18 Sep 2026
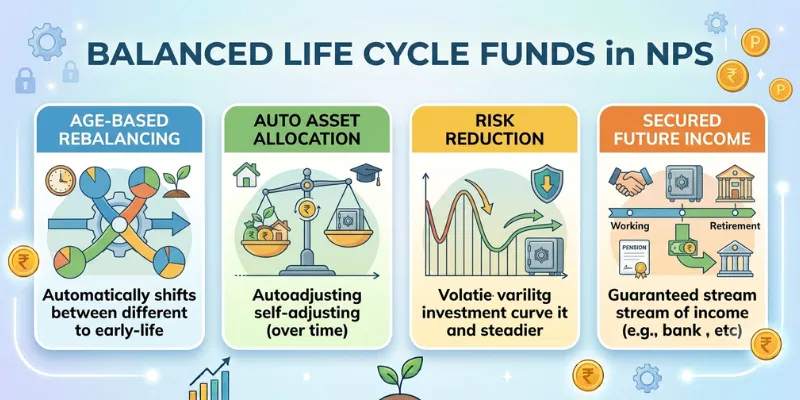
Balanced Life Cycle Funds in NPS are age-based investment options that automatically divide contributions among equity, corporate bonds, and government securities. They are designed to keep equity exposure higher for a longer period while gradually reducing risk as retirement approaches. Under the current structure, equity can remain at 50% up to age 45 and then reduce over time. This automatic approach removes the need for subscribers to manage asset allocation manually. It can support long-term retirement growth while maintaining diversification.
1. What Are Balanced Life Cycle Funds in NPS?
Balanced Life Cycle Funds in NPS are age-based investment options available under Auto Choice. They automatically divide a subscriber’s contributions among equity, corporate bonds, and government securities according to age.
1. Automatic Asset Allocation
The fund automatically decides how much money goes into each asset class. Subscribers do not need to select or change the percentages manually. This makes retirement investing easier for beginners.
2. Higher Equity for Longer
This option keeps a meaningful part of the portfolio invested in equity for a longer period. Equity exposure can remain at 50% up to age 45 under the current structure. This may provide better long-term growth potential, but it also increases market risk.
3. Gradual Risk Reduction
After age 45, the equity allocation starts reducing gradually. At the same time, investment in corporate bonds and government securities increases. This helps lower market risk as the subscriber moves closer to retirement.
4. Part of Auto Choice
Balanced Life Cycle Funds in NPS come under the Auto Choice investment category. The system automatically rebalances the portfolio based on the subscriber’s age. It may suit people who do not want to manage their NPS allocation regularly.
5. Market-Linked Investment
Returns from this fund are not fixed or guaranteed. Performance depends on equity markets, bond markets, interest rates, and the selected Pension Fund Manager. Subscribers should understand their risk capacity before choosing this option.
6. Current Fund Name
The earlier Balanced Life Cycle Fund is now commonly shown under the aggressive life-cycle category. Although the official name may change, many subscribers still recognise it by its earlier name. Its main feature remains longer equity exposure with automatic age-based reduction.
2. Why Was the Balanced Life Cycle Fund Introduced?
The Balanced Life Cycle Fund was introduced to give NPS subscribers higher equity exposure for a longer period. Traditional life-cycle funds usually start reducing equity after age 35. This option keeps equity at a higher level until age 45 to support long-term growth. After that, the equity share gradually decreases as retirement comes closer. It also removes the need for subscribers to manage asset allocation manually. The main goal of Balanced Life Cycle Funds in NPS is to balance growth potential with age-based risk reduction.
3. How Do Balanced Life Cycle Funds in NPS Work?
Balanced Life Cycle Funds in NPS work under the Auto Choice investment option. The subscriber’s contributions are automatically divided among equity, corporate bonds, and government securities. The asset allocation changes according to the subscriber’s age. Equity remains higher during the early and middle working years to support long-term growth. Subscribers do not need to select percentages or rebalance the portfolio manually. The system manages the investment mix according to the prescribed age-based structure.
After age 45, the equity allocation starts reducing gradually. At the same time, the share of corporate bonds and government securities increases. This process lowers market exposure as the subscriber moves closer to retirement. The remaining portfolio still stays diversified across growth and debt assets. Returns depend on market performance and are not fixed or guaranteed. This automatic process makes retirement investing simpler for subscribers who prefer less manual management. You can also use an nps calculator to estimate how regular contributions and expected returns may grow your retirement corpus over time.
4. Asset Classes Used in Balanced Life Cycle Funds
Balanced Life Cycle Funds in NPS invest the subscriber’s money across different asset classes. Each asset class has a separate role in balancing growth, income, and risk.
1. Equity – Asset Class E
Equity invests mainly in shares of companies. It offers higher long-term growth potential, but its value can rise or fall with the stock market. This asset class helps subscribers build a larger retirement corpus over time.
2. Corporate Bonds – Asset Class C
Corporate bonds invest in debt securities issued by companies. They usually provide more stability than equity and may generate regular interest-based returns. However, they can still face credit risk and interest-rate risk.
3. Government Securities – Asset Class G
Government securities invest in bonds issued by the central or state governments. They generally carry lower credit risk than corporate bonds. Their market value can still change when interest rates move.
4. Role of Diversification
The fund spreads money across equity, corporate bonds, and government securities instead of depending on one asset class. This diversification can reduce overall portfolio risk. It also helps Balanced Life Cycle Funds in NPS maintain a better balance between growth and stability.
5. Age-Wise Asset Allocation
The asset allocation in Balanced Life Cycle Funds in NPS changes automatically with the subscriber’s age. The fund keeps equity at 50% up to age 45 and then gradually shifts money toward corporate bonds and government securities. The current official name of this option is Life Cycle – Aggressive (35E/55Y).
1. Allocation Up to Age 45
The fund keeps 50% of the portfolio in equity up to age 45. Corporate bonds receive 30%, while government securities receive 20%. This allocation focuses on long-term growth while maintaining some stability through debt investments.
2. Allocation Between Age 46 and 50
After age 45, the equity percentage starts reducing every year. At age 46, equity falls to 48%, and it reaches 40% at age 50. Government securities gradually increase during the same period to reduce overall market risk.
3. Allocation Between Age 51 and 54
Equity continues to fall slowly from 39% at age 51 to 36% at age 54. Corporate bond allocation also decreases, while government securities receive a larger share. This creates a more stable portfolio as retirement approaches.
4. Allocation at Age 55 and Above
At age 55 and above, the fund maintains 35% in equity, 10% in corporate bonds, and 55% in government securities. It still keeps meaningful equity exposure for future growth. However, most of the portfolio moves toward government securities for greater stability.
This age-based structure allows Balanced Life Cycle Funds in NPS to provide higher equity exposure during the working years and gradually reduce risk closer to retirement. You can calculate your nps growth by entering your age, contribution amount, expected return, and investment period in an online tool.
6. Equity Tapering in Balanced Life Cycle Funds
Equity tapering means gradually reducing the amount invested in shares as the subscriber gets older. In Balanced Life Cycle Funds in NPS, equity remains at 50% up to age 45 and starts decreasing after that. This allows subscribers to stay invested in growth-focused assets for a longer period. At the same time, it avoids keeping the same high equity exposure close to retirement.
1. Tapering Starts After Age 45
Traditional life-cycle options usually start reducing equity at an earlier age. In this fund, the reduction begins only after age 45. This gives subscribers more time to benefit from long-term market growth.
2. Equity Reduces Gradually
The equity share does not fall suddenly. It decreases step by step every year after age 45. This gradual change helps avoid a major shift in the portfolio at one time.
3. Debt Allocation Increases
As equity decreases, more money moves toward corporate bonds and government securities. These assets are generally more stable than equity. This helps reduce market risk as retirement comes closer.
4. Risk Is Reduced With Age
Younger subscribers usually have more time to recover from market falls. Older subscribers have less time before retirement, so lower equity exposure may be safer. Equity tapering follows this age-based risk approach.
5. Automatic Rebalancing
Subscribers do not need to reduce equity manually every year. The fund automatically adjusts the asset mix according to the prescribed age table. This makes Balanced Life Cycle Funds in NPS easier for people who prefer automatic portfolio management.
7. Balanced Life Cycle Fund vs LC75
Both options come under Auto Choice, but they follow different equity-reduction patterns. Balanced Life Cycle Funds in NPS keep moderate equity exposure for longer, while LC75 starts with higher equity and reduces it earlier.
1. Equity Allocation at a Young Age
LC75 invests up to 75% in equity for subscribers aged up to 35. The Balanced Life Cycle Fund keeps equity at 50% during this stage. Therefore, LC75 usually carries greater market risk and growth potential during the early years.
2. Age at Which Equity Reduction Starts
LC75 starts reducing equity after age 35. In comparison, the Balanced Life Cycle Fund maintains 50% equity up to age 45. This ten-year difference is one of the most important points between the two options.
3. Equity Exposure at Age 45
By age 45, LC75 has already reduced its equity allocation because tapering began ten years earlier. The Balanced option still maintains 50% equity at this age. Therefore, it provides greater equity exposure during the subscriber’s later working years.
4. Equity Exposure Near Retirement
At age 55 and above, LC75 generally holds 15% equity. The Balanced Life Cycle Fund maintains 35% equity at the same stage. This gives the Balanced option higher growth potential but also exposes the subscriber to more market fluctuations near retirement.
8. Balanced Life Cycle Fund vs LC50
Both options come under Auto Choice and can invest up to 50% in equity during the early stage. However, Balanced Life Cycle Funds in NPS keep this equity exposure for longer, while LC50 starts reducing it after age 35.
1. Initial Equity Allocation
Both funds can maintain 50% equity during the subscriber’s younger years. This gives them similar growth potential at the beginning. The main difference appears when the subscriber crosses age 35.
2. Equity Reduction Age
LC50 starts reducing equity after age 35. The Balanced Life Cycle Fund continues with 50% equity up to age 45. Therefore, it provides ten additional years of higher equity exposure.
3. Allocation During Middle Age
By age 45, LC50 has already shifted a larger part of the portfolio toward debt assets. The Balanced option still maintains half of the portfolio in equity. This may support higher growth, but it also creates greater market risk.
4. Allocation Near Retirement
At age 55 and above, LC50 generally reduces equity to 10%. The Balanced Life Cycle Fund keeps 35% in equity at the same age. This means the Balanced option remains more exposed to market movements near retirement.
5. Risk and Stability
LC50 gradually becomes more conservative as the subscriber gets older. It may provide greater stability during the later working years. The Balanced option carries more risk but may offer better long-term growth potential.
6. Which Option Is Better?
LC50 may suit subscribers who want moderate risk and stronger debt allocation closer to retirement. Balanced Life Cycle Funds in NPS may suit people who can tolerate market fluctuations and want equity exposure to remain higher after age 45. The final choice should match the subscriber’s age, risk capacity, retirement period, and other investments.
9. Advantages and Disadvantages of Balanced Life Cycle Funds
Balanced Life Cycle Funds in NPS offer automatic age-based investing, but they also carry market-related risks. Subscribers should understand both sides before selecting this option.
1. Advantages
- Keeps equity exposure higher for a longer period.
- Automatically changes asset allocation according to age.
- Reduces the need for manual portfolio management.
- Provides diversification across equity, corporate bonds, and government securities.
- Gradually lowers market risk as retirement approaches.
2. Disadvantages
- Higher equity exposure can cause short-term losses.
- It may be too risky for conservative subscribers.
- Returns are market-linked and not guaranteed.
- The fixed age-based allocation may not match every personal situation.
- Subscribers get less control than they would under Active Choice.
10. How to Select Balanced Life Cycle Funds in NPS
Subscribers can select Balanced Life Cycle Funds in NPS through the investment preference section of their NPS account. The option may appear under its current name, Life Cycle – Aggressive.
1. Log In to Your NPS Account
Open the CRA portal linked to your PRAN and log in with your credentials. Go to the section for changing scheme preference or investment choice.
2. Choose Auto Choice
Select Auto Choice instead of Active Choice. Auto Choice manages the asset allocation automatically according to the subscriber’s age.
3. Select Life Cycle – Aggressive
Choose Life Cycle – Aggressive, which is the current name used for the earlier Balanced Life Cycle Fund. Check the age-wise equity and debt allocation before confirming the option.
4. Choose a Pension Fund Manager
Select an available Pension Fund Manager according to your preference. Compare long-term performance, consistency, and service rather than focusing only on recent returns.
5. Complete Verification
Review the selected option and submit the request. Complete OTP, e-signature, or other verification required by the CRA.
6. Check the Updated Allocation
After the request is processed, check your transaction statement or account dashboard. Confirm that the new life-cycle option and asset allocation are displayed correctly.
11. Who Should Avoid Balanced Life Cycle Funds in NPS?
Balanced Life Cycle Funds in NPS may not suit every subscriber because they keep meaningful equity exposure even during later working years. People with low risk capacity or a short retirement period should review safer options.
1. Highly Conservative Investors
Subscribers who feel uncomfortable with stock market fluctuations may want to avoid this option. Equity can fall sharply during weak market periods. A lower-equity life-cycle fund may provide better peace of mind.
2. Subscribers Close to Retirement
People with only a few years left before retirement may not have enough time to recover from a major market fall. This fund keeps 35% equity even at age 55 and above. Such subscribers should compare more conservative options before choosing it.
3. People With Low Risk Capacity
Some investors may understand market risk but cannot financially handle a temporary fall in their corpus. This may happen when NPS is their main retirement asset. They may need a portfolio with greater debt allocation and lower volatility.
4. Subscribers Who Need Full Control
This option follows a fixed age-based allocation. Subscribers cannot freely set every asset percentage under the same structure. People who want complete control over equity and debt may prefer Active Choice.
5. People Depending Only on NPS
Subscribers who have no other retirement savings should be more careful with higher equity exposure. A market decline near retirement can affect their available corpus. They should consider emergency savings, other stable investments, and expected pension needs before selecting this fund.
The decision to avoid Balanced Life Cycle Funds in NPS should depend on risk tolerance, retirement period, other investments, and financial responsibilities.
The Balanced Life Cycle Fund is currently listed as Life Cycle – Aggressive (35E/55Y). It remains an age-based investment option under Auto Choice. Many subscribers still know it by its earlier Balanced Life Cycle Fund name.
The fund keeps 50% of the portfolio in equity up to age 45. After that, equity gradually reduces with age. It reaches 35% at age 55 and above.
Yes, it is one of the life-cycle options available under Auto Choice. The system automatically divides money among equity, corporate bonds, and government securities. It also changes the allocation according to the subscriber’s age.
No, returns are not fixed or guaranteed. Performance depends on stock markets, bond markets, interest rates, and the selected Pension Fund Manager. The value of the retirement corpus can rise or fall over time.
It has lower equity than LC75 during the early years because it starts with 50% instead of 75%. However, it keeps more equity than LC75 during later ages because its reduction starts after age 45. Therefore, the safer option can depend on the subscriber’s current age and risk capacity.
Eligible subscribers can generally change their investment preference through the CRA account, subject to current NPS rules. They may switch to another Auto Choice option or consider Active Choice. Avoid changing only because of short-term market movements.
Conclusion
So guys, in this article, we’ve covered Balanced Life Cycle Funds in NPS in detail. We discussed how these funds work, their age-wise allocation, equity tapering, asset classes, benefits, risks, and comparison with LC50 and LC75. In my opinion, this option may suit subscribers who want automatic management and can handle meaningful equity exposure even during later working years. Conservative investors should compare lower-risk life-cycle options before making a decision. Review your age, retirement period, and risk capacity today before selecting the right NPS fund.
The information and calculators on Finance Calculatorz are provided for educational purposes only. Calculator results are estimates and may not always be fully accurate. This content is not financial, investment, tax, or legal advice. Please consult a qualified professional before making any financial decision.
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
