NPS Tax Benefits for Salaried and Self Employed Persons
Published: 21 Sep 2026
NPS Tax Benefits help eligible subscribers reduce taxable income while building long-term retirement savings. These benefits mainly apply to personal contributions, employer contributions, partial withdrawals, and retirement proceeds. Different sections, including 80CCD(1), 80CCD(1B), and 80CCD(2), provide separate deductions. The available benefit also depends on whether the taxpayer follows the old or new tax regime. Understanding these rules can help investors plan taxes more effectively.
1. What Are NPS Tax Benefits?
NPS Tax Benefits are tax deductions and exemptions available to eligible subscribers of the National Pension System. These benefits help people reduce their taxable income while building retirement savings.
1. Tax Benefits on Personal Contributions
Subscribers may claim tax deductions on eligible personal contributions made to their NPS Tier 1 account. The available deduction depends on the tax regime, contribution amount, and applicable income-tax section.
2. Tax Benefits on Employer Contributions
Employer contributions may also qualify for a separate tax deduction. This benefit is mainly useful for salaried employees whose companies contribute to their NPS account.
3. Tax Relief on Withdrawals
Certain partial withdrawals and a permitted portion of the retirement corpus may receive tax exemption. However, the withdrawal must follow the applicable NPS rules and conditions.
4. Tax on Annuity Income
A part of the retirement corpus may be used to purchase an annuity. The amount used to buy the annuity may receive tax relief, but the pension income received later is generally taxable.
5. Purpose of NPS Tax Advantages
The main purpose of NPS Tax Benefits is to encourage long-term retirement planning. These benefits make NPS useful for people who want to save tax and create a retirement fund at the same time.
2. Main Sections Covering NPS Tax Benefits
Three main sections of the Income Tax Act cover NPS Tax Benefits. Each section applies to a different type of contribution and follows separate limits.
1. Section 80CCD(1)
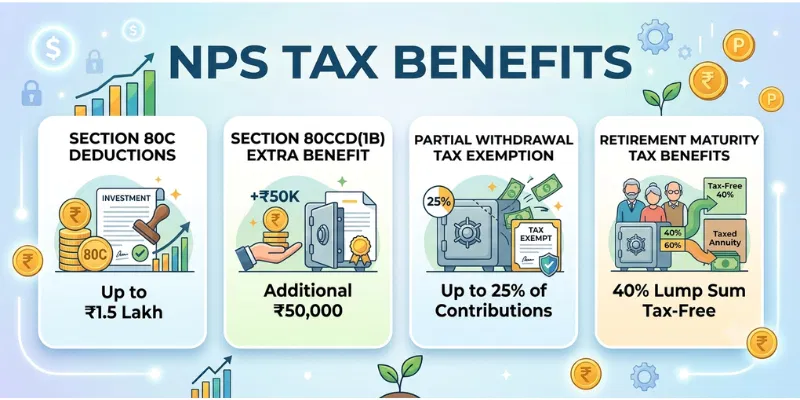
Section 80CCD(1) covers contributions made by the subscriber to an nps tier 1 account. Salaried employees can claim a deduction based on their eligible salary, while self-employed people follow a limit based on gross total income. This deduction forms part of the overall ₹1.5 lakh limit under Section 80CCE. It is generally available only under the old tax regime.
2. Section 80CCD(1B)
Section 80CCD(1B) provides an additional deduction of up to ₹50,000 for eligible personal NPS contributions. This amount is available over and above the ₹1.5 lakh overall limit. It is one of the most important NPS Tax Benefits for people using the old tax regime. However, this deduction is generally not available under the new tax regime.
3. Section 80CCD(2)
Section 80CCD(2) covers contributions made by an employer to an employee’s NPS Tier 1 account. This deduction is separate from the ₹1.5 lakh limit and the additional ₹50,000 deduction. Eligible employer contributions may also qualify under the new tax regime, unlike personal contributions under Sections 80CCD(1) and 80CCD(1B). The available amount depends on salary, employer category, and current tax rules.
4. Quick Comparison
| Tax Section | Contribution Made By | Main Benefit |
|---|---|---|
| Section 80CCD(1) | Subscriber | Deduction within the ₹1.5 lakh overall limit |
| Section 80CCD(1B) | Subscriber | Additional deduction of up to ₹50,000 |
| Section 80CCD(2) | Employer | Separate deduction for eligible employer contributions |
3. NPS Tax Benefits Under the Old Tax Regime
The old tax regime allows subscribers to claim deductions on eligible personal and employer NPS contributions. These NPS Tax Benefits can reduce taxable income, but every deduction follows a separate limit and condition.
1. Deduction Under Section 80CCD(1)
A subscriber’s personal contribution to an NPS Tier 1 account may qualify under Section 80CCD(1). Salaried employees can claim up to 10% of their eligible salary, while self-employed people can claim up to 20% of gross total income. However, this deduction forms part of the combined ₹1.5 lakh limit under Section 80CCE.
2. Additional Deduction Under Section 80CCD(1B)
Subscribers can claim an additional deduction of up to ₹50,000 for eligible personal NPS contributions. This benefit is available over and above the ₹1.5 lakh combined limit. It is one of the main NPS Tax Benefits available under the old tax regime.
3. Employer Contribution Under Section 80CCD(2)
Eligible employer contributions to an employee’s Tier 1 account may qualify for a separate deduction. Under the old tax regime, the current limit is generally up to 10% of eligible salary. This deduction does not form part of the normal ₹1.5 lakh limit.
4. Possible Total Deduction
An eligible taxpayer may claim up to ₹1.5 lakh within the Section 80CCE limit and an additional ₹50,000 under Section 80CCD(1B). Employer contributions may provide a separate deduction under Section 80CCD(2). Therefore, the total benefit can be higher than ₹2 lakh when an employer also contributes to NPS.
5. Important Conditions
These deductions mainly apply to eligible Tier 1 contributions. The same contribution cannot be claimed twice under different sections. Subscribers should also check their salary, income, contribution amount, and other deductions before calculating the final tax benefit.
4. NPS Tax Benefits Under the New Tax Regime
The new tax regime offers fewer deductions on personal investments. However, salaried employees can still receive NPS Tax Benefits when their employer contributes to their NPS Tier 1 account.
1. No Deduction Under Section 80CCD(1)
Personal contributions made by an employee or self-employed person generally do not qualify under Section 80CCD(1) in the new tax regime. This means subscribers cannot claim their own NPS contribution within the ₹1.5 lakh deduction limit.
2. No Additional ₹50,000 Deduction
The additional deduction of up to ₹50,000 under Section 80CCD(1B) is also generally unavailable under the new tax regime. Subscribers who invest their own money in NPS cannot claim this extra deduction while following the new regime.
3. Employer Contribution Under Section 80CCD(2)
Eligible contributions made by an employer to an employee’s NPS Tier 1 account can still qualify for a deduction. This benefit is available separately under Section 80CCD(2). Therefore, employer contributions are the main NPS Tax Benefits available under the new tax regime.
4. Deduction Limit for Employer Contribution
Under the new tax regime, an eligible employee can claim an employer contribution of up to 14% of salary. Salary generally includes Basic Salary and Dearness Allowance where applicable. The deduction is subject to the actual amount contributed by the employer and the current income-tax rules.
5. Example
Suppose an employee’s eligible Basic Salary and Dearness Allowance total ₹8,00,000 per year. If the employer contributes ₹1,12,000 to the employee’s NPS Tier 1 account, the full contribution may qualify because it equals 14% of the eligible salary. However, a personal contribution of ₹50,000 would generally not provide a separate deduction under the new tax regime.
6. Important Point
The new tax regime may suit people who have fewer investments and deductions. However, taxpayers should compare their income, employer contribution, tax rates, and available deductions before selecting a regime. They should not choose the new regime only because it allows an employer NPS deduction.
5. Old vs New Tax Regime for NPS
The availability of NPS Tax Benefits depends greatly on the tax regime selected by the taxpayer. The old regime allows deductions for personal and employer contributions, while the new regime mainly provides a deduction for eligible employer contributions.
1. Quick Comparison
| Comparison Point | Old Tax Regime | New Tax Regime |
|---|---|---|
| Section 80CCD(1) | Available for eligible personal contributions | Generally not available |
| Section 80CCD(1B) | Additional deduction of up to ₹50,000 available | Not available |
| Section 80CCD(2) | Available for eligible employer contributions | Available for eligible employer contributions |
| Personal NPS tax saving | Higher deduction opportunities | No deduction on personal contribution |
| Employer contribution limit | Generally 10% of salary for private-sector employees and 14% for government employees | Up to 14% of salary for eligible employees |
| Other common deductions | Many deductions are available | Most deductions are restricted |
| Best suited for | People with high eligible deductions | People with fewer deductions or employer NPS support |
2. Personal Contribution Benefits
Under the old tax regime, subscribers may claim eligible personal contributions under Sections 80CCD(1) and 80CCD(1B). These deductions can provide total personal NPS Tax Advantages of up to ₹2 lakh, subject to applicable limits and conditions.
The new tax regime generally does not allow either of these personal contribution deductions. Therefore, investing your own money in NPS may help build a retirement fund, but it will not normally reduce taxable income under the new regime.
3. Employer Contribution Benefits
Section 80CCD(2) is available under both tax regimes. Under the old regime, the deduction limit is generally 10% of eligible salary for private-sector employees and 14% for Central or State Government employees.
Under the new regime, eligible employer contributions may qualify for a deduction of up to 14% of salary. Salary generally means Basic Salary plus Dearness Allowance where applicable.
4. Availability of Other Deductions
The old regime allows taxpayers to claim several deductions and exemptions, including eligible benefits under Sections 80C, 80D, and 80CCD. This may make it suitable for people who regularly invest, pay insurance premiums, or claim other permitted deductions.
The new regime offers lower slab rates but restricts most common deductions. However, the employer contribution deduction under Section 80CCD(2) remains one of the important NPS Tax Benefits available in this regime.
5. Which Tax Regime Is Better for NPS?
The old regime may be more suitable for people who make personal NPS contributions and have several other eligible deductions. It allows subscribers to use both the ₹1.5 lakh combined limit and the additional ₹50,000 deduction.
The new regime may suit employees whose employers contribute to their NPS accounts and who do not have many other deductions. However, taxpayers should calculate their total tax under both regimes before making a decision.
6. Important Point
Neither tax regime is automatically better for every subscriber. The right choice depends on income, personal investments, employer contributions, tax slab, and other deductions. Compare the complete tax liability instead of selecting a regime only for its NPS Tax Advantages.
6. NPS Tax Benefits for Salaried Employees
Salaried employees can receive NPS Tax Benefits on their own contributions and contributions made by their employer. However, the available deduction depends on the selected tax regime, salary structure, and contribution type.
1. Employee’s Own Contribution
Under the old tax regime, a salaried employee may claim a deduction for personal contributions made to an NPS Tier 1 account. The deduction under Section 80CCD(1) is limited to 10% of eligible salary and also forms part of the combined ₹1.5 lakh limit under Section 80CCE. Eligible salary generally includes Basic Salary and Dearness Allowance.
2. Additional ₹50,000 Deduction
A salaried employee using the old tax regime may claim an additional deduction of up to ₹50,000 under Section 80CCD(1B). This benefit is available over and above the normal ₹1.5 lakh combined limit. It is one of the most useful NPS Tax Benefits for employees who want to increase retirement savings and reduce taxable income.
3. Employer Contribution Benefit
Contributions made by an employer to an employee’s Tier 1 account may qualify separately under Section 80CCD(2). This deduction does not fall within the normal ₹1.5 lakh limit. It can provide an extra tax benefit without using the employee’s personal deduction limit.
4. Benefit Under the Old Tax Regime
Under the old tax regime, private-sector employees can generally claim eligible employer contributions up to 10% of salary. Central and State Government employees can claim up to 14% of eligible salary. These limits apply to the actual contribution made by the employer.
5. Benefit Under the New Tax Regime
Under the new tax regime, personal deductions under Sections 80CCD(1) and 80CCD(1B) are generally unavailable. However, eligible employer contributions under Section 80CCD(2) can still be claimed. The current limit under the new regime is up to 14% of salary for eligible employees.
7. NPS Tax Benefits for Self-Employed People
Self-employed individuals can use NPS Tax Benefits on eligible personal contributions made to a Tier 1 account. However, these deductions are mainly available under the old tax regime.
1. Deduction Under Section 80CCD(1)
A self-employed person may claim a deduction of up to 20% of gross total income under Section 80CCD(1). This deduction forms part of the combined ₹1.5 lakh limit under Section 80CCE. The final claim depends on the actual NPS contribution and available deduction limit.
2. Additional ₹50,000 Deduction
An additional deduction of up to ₹50,000 may be claimed under Section 80CCD(1B). This amount is available over and above the normal ₹1.5 lakh limit. The same contribution cannot be claimed under both Section 80CCD(1) and Section 80CCD(1B).
3. Benefit Under the Old Tax Regime
Personal NPS Tax Advantages are generally available when a self-employed taxpayer selects the old tax regime. People earning income from a business or profession must follow the prescribed process and deadline when opting out of the default new regime.
4. No Employer Contribution Deduction
Self-employed people normally cannot claim Section 80CCD(2) because they do not have an employer making contributions on their behalf. This section applies to eligible employer contributions to an employee’s NPS account. Therefore, self-employed subscribers mainly depend on Sections 80CCD(1) and 80CCD(1B).
8. NPS Tier 1 Tax Benefits
NPS Tier 1 is the main retirement account under the National Pension System. Most NPS Tax Benefits apply to eligible contributions and withdrawals from this account.
1. Deduction on Personal Contributions
Under the old tax regime, personal contributions to an NPS Tier 1 account may qualify under Section 80CCD(1). Salaried employees can claim up to 10% of eligible salary, while self-employed people can claim up to 20% of gross total income. This deduction forms part of the combined ₹1.5 lakh limit under Section 80CCE.
2. Additional ₹50,000 Deduction
Subscribers using the old tax regime may claim an additional deduction of up to ₹50,000 under Section 80CCD(1B). This deduction is available over and above the normal ₹1.5 lakh combined limit. It is one of the key NPS Tax Benefits linked to the Tier 1 account.
3. Employer Contribution Benefit
An eligible employer contribution to an employee’s Tier 1 account may qualify separately under Section 80CCD(2). This benefit is available under both tax regimes, although the permitted percentage depends on the employee category and selected regime. Under the new tax regime, eligible employer contributions can qualify up to 14% of salary.
4. Tax-Free Growth
Returns earned within the NPS Tier 1 account are not taxed every year while the money remains invested. This allows contributions and investment returns to grow together over the long term. However, NPS is market-linked, so the account value can rise or fall according to investment performance.
5. Tax Relief on Partial Withdrawal
An eligible partial withdrawal may be tax-exempt up to 25% of the subscriber’s own contributions. The subscriber must follow the permitted withdrawal conditions and purposes under the applicable NPS rules. Investment returns are not included while calculating this 25% limit.
9. NPS Tier 2 Tax Benefits
nps tier 2 is a voluntary investment account that offers easy deposits and withdrawals. However, regular Tier 2 accounts do not provide the same NPS Tax Benefits available with Tier 1.
1. No Deduction on Regular Contributions
Contributions made to a regular NPS Tier 2 account do not qualify for deductions under Sections 80CCD(1), 80CCD(1B), or 80CCD(2). Subscribers cannot claim the additional ₹50,000 deduction on these deposits. This rule applies even when the subscriber already has an active Tier 1 account.
2. Tax Treatment of Investment Returns
Regular Tier 2 investment returns do not receive a special tax exemption. The gains may be taxed according to the applicable income-tax rules and the subscriber’s tax position. Therefore, investors should not treat Tier 2 returns as automatically tax-free.
3. Tier 2 Tax Saver Scheme
A special Tier 2 Tax Saver Scheme is available to eligible Central Government employees. Contributions under this scheme may qualify for a deduction under Section 80C, subject to the overall limit and applicable conditions. This special scheme is different from a regular Tier 2 account.
4. Lock-In and Withdrawal Rules
A regular Tier 2 account generally allows subscribers to withdraw money whenever needed. The special Tax Saver Tier 2 Scheme follows a lock-in period, which limits withdrawals during that time. This flexibility is the main benefit of regular Tier 2, even though it offers fewer NPS Tax Advantages.
5. Tier 1 vs Tier 2 Tax Benefits
Tier 1 is mainly designed for retirement and provides deductions on eligible personal and employer contributions. Regular Tier 2 focuses more on flexible investing and liquidity rather than tax saving. Subscribers who want tax deductions should usually consider Tier 1, while Tier 2 may suit those who need easier access to their money.
10. Documents Required to Claim NPS Tax Benefits
You should keep proper records while claiming NPS Tax Benefits in your income tax return. These documents help verify personal contributions, employer contributions, and the deduction amount.
1. NPS Contribution Receipt
Keep the receipt for every personal contribution made to your NPS Tier 1 account. It shows the contribution date, amount, and transaction details. You can usually download it from the NPS portal or your account statement.
2. NPS Transaction Statement
The annual transaction statement provides a complete record of contributions made during the financial year. It may include personal deposits, employer contributions, units purchased, and account value. This document is useful for matching the deduction amount with your tax return.
3. Form 16
Salaried employees should check Form 16 issued by their employer. It may show the employer’s NPS contribution and the deduction considered under Section 80CCD(2). Employees should compare these details with their NPS statement before filing the return.
4. Salary Slips
Salary slips can help confirm employer contributions deducted or deposited through payroll. They may also show Basic Salary and Dearness Allowance, which are used for certain percentage-based limits. Keep the salary slips for the months in which NPS contributions were made.
5. PRAN and Bank Payment Proof
Keep your Permanent Retirement Account Number and bank statements showing NPS payments. These records can support your claim if contribution details are missing or unclear. Proper documents make it easier to claim NPS Tax Benefits correctly and avoid mistakes during tax verification.
11. Common Mistakes While Claiming NPS Tax Benefits
Avoid these common mistakes when claiming NPS Tax Benefits:
- Claiming Section 80CCD(1) or 80CCD(1B) under the new tax regime.
- Claiming the same NPS contribution under more than one tax section.
- Including regular Tier 2 contributions in the NPS deduction claim.
- Ignoring the combined ₹1.5 lakh limit under Section 80CCE.
- Forgetting to match contribution receipts, Form 16, and the NPS statement before filing the return.
Under the old tax regime, eligible personal contributions may provide deductions of up to ₹2 lakh. This includes the shared ₹1.5 lakh limit and an additional ₹50,000 under Section 80CCD(1B). Employer contributions may provide a separate deduction under Section 80CCD(2).
Personal NPS contributions generally do not provide deductions under the new tax regime. However, an eligible employer contribution may qualify under Section 80CCD(2). Self-employed subscribers cannot use this employer contribution benefit.
Regular Tier 2 contributions generally do not qualify for common NPS deductions. A special Tier 2 Tax Saver Scheme may provide benefits to eligible Central Government employees. Subscribers should not confuse this special scheme with a regular Tier 2 account.
An eligible portion of the NPS corpus may be withdrawn tax-free at retirement. The amount used to purchase an annuity is generally not taxed at the time of purchase. However, the pension received from the annuity is normally taxable.
Both may claim eligible personal contributions under Sections 80CCD(1) and 80CCD(1B) under the old regime. However, their percentage limits under Section 80CCD(1) are different. Only salaried employees can normally receive a separate employer contribution deduction.
Conclusion
So guys, in this article, we’ve covered NPS Tax Benefits in detail. We discussed tax deductions under different sections, old and new tax regime rules, benefits for salaried and self-employed people, Tier 1 and Tier 2 taxation, required documents, and common mistakes. In my opinion, NPS can be a useful option for people who want to save tax while building a long-term retirement fund. However, you should always compare both tax regimes and check the latest rules before claiming any deduction. Review your income, contribution type, and retirement goals today before investing in NPS.
The information and calculators on Finance Calculatorz are provided for educational purposes only. Calculator results are estimates and may not always be fully accurate. This content is not financial, investment, tax, or legal advice. Please consult a qualified professional before making any financial decision.
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
- Be Respectful
- Stay Relevant
- Stay Positive
- True Feedback
- Encourage Discussion
- Avoid Spamming
- No Fake News
- Don't Copy-Paste
- No Personal Attacks
